


This is a detailed research piece. If you find value in institutional-quality hedge fund analysis, support this work on Patreon.
Two Sigma’s Shanghai unit crossed RMB 10 billion ($1.4 billion) AUM in November 2025 — only the second foreign manager alongside Bridgewater to reach this threshold in China’s RMB 6 trillion onshore hedge fund market. The catalyst: a CSI 500 index-enhanced strategy delivering 52.5% YTD returns through September, with reported alpha of 23 percentage points versus benchmark.
Market Structure: The Alpha Source
China’s A-share market inverts developed-market norms. Retail investors hold ~25% of shares but generate ~80% of daily trading volume. Average retail holding period: 40 days versus 109 days for institutions.
This creates exploitable inefficiencies: attention-driven buying, momentum overshoots, and predictable behavioral patterns around news events. The CSI 500–500 mid-cap A-shares excluding CSI 300 constituents — offers the optimal combination of liquidity (sufficient for billion-dollar strategies) and inefficiency (thin analyst coverage, high cross-sectional volatility).
Strategy Architecture
Two Sigma operates two onshore products via its Shanghai WFOE (PFM registration: September 2019):
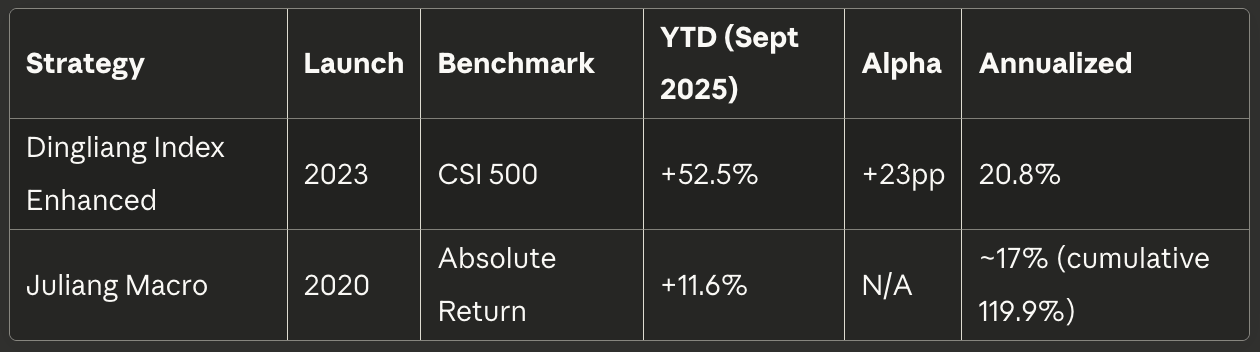
Dingliang mechanics: Index enhancement maintains full market exposure (beta ≈ 1) while overweighting high-conviction names and underweighting low-conviction positions within the CSI 500 universe. Tracking error is controlled; alpha derives from stock selection, not macro bets.
Likely alpha sources:
Factor tilts (quality, value, momentum — all show elevated efficacy in retail-dominated markets)
CSI 500 rebalancing arbitrage (semi-annual reconstitution creates predictable flow patterns)
Alternative data integration (10,000+ data sources globally)
Return Attribution
Bloomberg reported +52.5% total return and +23pp excess versus benchmark. The implied CSI 500 benchmark return (~29.5%) exceeds some publicly quoted ETF YTD figures (22–24%), suggesting Two Sigma may use a total-return index series (with dividends reinvested) rather than price-only. Exact methodology unconfirmed; the 23pp alpha figure originates from Bloomberg’s reporting.
Key point: Whether alpha is 23pp or higher (if benchmark returned less), the magnitude of outperformance is exceptional for index-enhanced strategies at this AUM scale.
Regulatory Environment
The CSRC intensified quant oversight after February 2024’s “quant quake”:
Lingjun Incident (Feb 19, 2024): RMB 2.57 billion sold in one minute at market open. Three-day trading ban imposed for “disrupting normal trading order.”
Wu Qing appointment (Feb 2024): New CSRC chairman known as “Broker Butcher” — prioritizes retail investor protection.
New restrictions: HFT scrutiny, mandatory algorithm disclosure requests, DMA leverage limits reduced to 1:1.
Foreign advantage: Two Sigma’s lower-frequency index enhancement strategy sidesteps HFT restrictions. Institutional compliance infrastructure absorbs rising regulatory costs that squeeze smaller domestic quants. Result: flight-to-quality capital flows toward established foreign WFOEs.
113 funds now manage >RMB 10 billion (vs. 91 at year-end 2024) — scale increasingly matters.
Infrastructure Moat
Two Sigma’s global platform provides competitive advantages difficult for domestic quants to replicate:
Data: 10,000+ sources, 380+ petabytes stored
Compute: Infrastructure ranking among world’s top 5 supercomputer sites
Simulation: 48,000+ daily simulations for stress testing and overfitting prevention
Execution: Order-slicing algorithms minimize market impact in illiquid small-caps
Note: Two Sigma’s website shows varying infrastructure figures across pages (380+ PB vs. 600+ PB on different sections) — numbers cited here reflect publicly stated ranges.
Capacity Constraint
Industry consensus: China quant alpha decays above ~$1 billion AUM due to market impact in small-caps. Two Sigma’s mitigation:
Multi-strategy diversification — equity (Dingliang) and macro (Juliang) access different liquidity pools
Global signal transfer — patterns from other retail-heavy markets (Korea, Taiwan) may apply to China
Dynamic universe expansion — likely flexibility to trade CSI 300 (liquidity) or CSI 1000 (alpha) as conditions warrant
Bottom Line
Two Sigma’s China performance validates a counterintuitive thesis: retail dominance amplifies quant edge rather than neutralizing it. Behavioral inefficiencies persist precisely because 80% of volume comes from participants with 40-day holding periods and attention-driven trading patterns.
The sustainable alpha question remains open as AUM scales. But the 52.5% return demonstrates that systematic strategies — when paired with superior infrastructure and execution — can harvest alpha in markets previously considered hostile to quantitative approaches.
Sources
Bloomberg (Nov 2025) — Two Sigma AUM, 52.5% return, 23pp alpha https://www.bloomberg.com/news/articles/2025-11-12/two-sigma-joins-china-hedge-fund-elite-after-strategy-soars-52
China Economic Review — Bridgewater comparison, 113 funds >RMB 10bn https://chinaeconomicreview.com/two-sigma-china-aum-passes-rmb10bn-for-first-time/
PRNewswire (Sept 2019) — PFM registration, WFOE incorporation https://www.prnewswire.com/news-releases/two-sigma-completed-private-fund-manager-registration-in-china-300922243.html
CNBC (Feb 2024) — Lingjun 3-day ban, RMB 2.57bn in 1 minute https://www.cnbc.com/2024/02/21/china-tightens-reins-on-quant-trading-after-three-day-ban-on-fund.html
Reuters via U.S. News (Mar 2024) — CSRC crackdown, Wu Qing appointment https://money.usnews.com/investing/news/articles/2024-03-15/chinas-quant-funds-conform-as-regulators-crack-down-after-crash
Annual Review of Financial Economics (Nov 2024) — Retail 80% volume, 25% holdings, 40-day avg holding https://www.annualreviews.org/content/journals/10.1146/annurev-financial-082123-110132
Two Sigma (official) — Infrastructure: 10,000+ data sources, 380+ PB, simulations https://www.twosigma.com/businesses/investment-management/
China Daily (Feb 2024) — Lingjun AUM >RMB 60bn, regulatory details https://www.chinadaily.com.cn/a/202402/23/WS65d7f1f5a31082fc043b8b08.html
Fund Selector Asia (Nov 2020) — Juliang Macro launch, first onshore product https://fundselectorasia.com/two-sigma-to-debut-onshore-quant-product/
Wikipedia — Company background, AUM history https://en.wikipedia.org/wiki/Two_Sigma
Disclaimer: Informational purposes only. Past performance does not guarantee future results. Author holds no positions in securities mentioned.
📊 Support this research: https://www.patreon.com/c/NavnoorBawa
Cover photograph: Ermell, CC0, via Wikimedia Commons.