


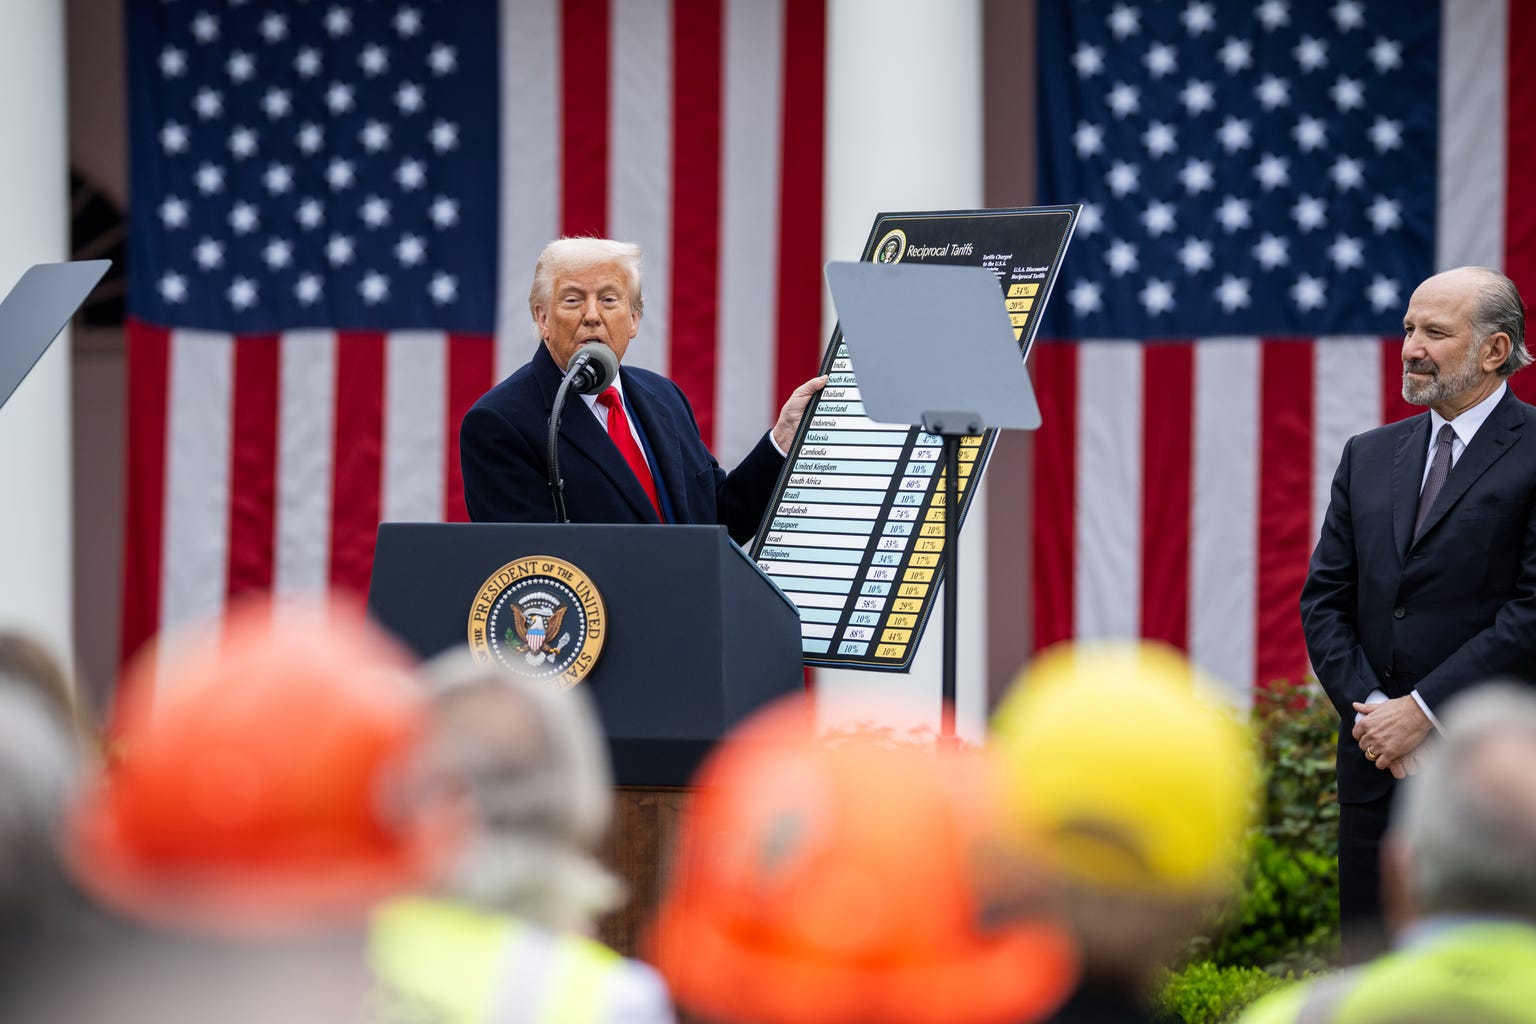
On April 2, 2025, President Trump stood in the White House Rose Garden and declared “Liberation Day” — announcing the most sweeping tariff regime since the 1930s Smoot-Hawley Act. Within hours, Renaissance Technologies’ flagship institutional fund had begun hemorrhaging money at a pace that would ultimately cost investors approximately $1.6 billion by month’s end.
The Renaissance Institutional Equities Fund (RIEF), managing approximately $20 billion in assets, suffered an 8% drawdown in April 2025 — a stunning collapse for a fund built on mathematical precision and systematic risk management. For an institution that had generated billions through pattern recognition and statistical arbitrage, Trump’s policy announcement represented something their models had never encountered: a true black swan event that broke every correlation assumption built into their algorithms.
The question isn’t whether Renaissance’s quants saw it coming — no one did. The question is why their systematic approach, which had weathered countless market storms, proved so vulnerable to a single policy announcement that was partially reversed within a week. The answer reveals fundamental truths about the limits of quantitative finance and the hidden risks embedded in factor-based strategies.
The Quant Colossus and Its Two Universes
Renaissance Technologies operates two distinct worlds. There’s Medallion — the employee-only fund that has reportedly generated 66% annual returns before fees from 1988–2021 — and then there’s everything else. RIEF belongs to that second category: the funds that external investors can access, but which have consistently underperformed their legendary sibling.
While Medallion trades with holding periods measured in hours or days, RIEF operates on a completely different timescale. According to regulatory filings, the fund typically holds positions for six months to one year, using factor-based risk models to hedge exposures and generate returns through systematic equity strategies. RIEF targets a beta of 0.4 or lower relative to the S&P 500, with leverage of approximately 2.5 to 1, maintaining no more than $100 net long for each $100 of equity.
This longer-term approach makes RIEF fundamentally different from its high-frequency cousin — and as April 2025 demonstrated, far more vulnerable to regime changes. The distinction matters because it explains why RIEF’s systematic models failed where Medallion’s ultra-short approach might have adapted more quickly to shifting market patterns.
Anatomy of Liberation Day: The Policy Shock That Broke Markets
Trump’s April 2 announcement wasn’t just another tariff adjustment. The administration imposed a 10% baseline tariff on virtually all imports, plus “reciprocal tariffs” ranging from 11% to 50% on specific countries based on existing trade barriers. China faced an initial 34% reciprocal rate, which when combined with existing 20% fentanyl-related duties, brought the total to 54%. The baseline tariff took effect April 5, with higher country-specific rates scheduled for April 9.
The market reaction was immediate and catastrophic. The S&P 500 plummeted 4.88% on April 3 alone — the day after Trump’s announcement — as investors fled risk assets. Government bonds, traditionally a safe haven, sold off simultaneously as traders moved to cash, creating the rare scenario of stocks and bonds falling together.
The panic proved so severe that Trump suspended the higher “reciprocal” tariffs on April 9 for all countries except China, leading to a dramatic market recovery with the S&P 500 surging 9.52% on the suspension announcement. However, China remained excluded from the relief, facing escalating rates that eventually peaked at 145% before being negotiated down to approximately 40% by July 2025.
For RIEF’s models, this created what quantitative analysts call a “correlation breakdown” — when historical relationships between asset classes suddenly invert or disappear entirely. The fund’s algorithms had learned from decades of data showing how different sectors, geographies, and factors typically behaved during market stress. But tariffs of this magnitude hadn’t existed since the 1930s, rendering that historical data essentially useless during the critical April 2–9 window.
The $1.6 Billion Unraveling: When Systematic Strategies Fail
RIEF’s 8% April loss translates to approximately $1.6 billion in destroyed value based on the fund’s estimated $20 billion in assets under management — a staggering sum that highlights both the scale of systematic trading and the magnitude of regime change vulnerability. Crucially, this massive loss occurred despite the tariff shock being partially reversed within a week, underscoring how quickly systematic strategies can unravel when their foundational assumptions break down.
The loss mechanism during the April 2–9 window reveals three critical vulnerabilities in factor-based quantitative strategies:
Regime Change Blindness: RIEF’s models were calibrated on decades of relatively free trade. The algorithms had learned to recognize patterns in a world where cross-border capital flows and supply chains operated under predictable rules. Trump’s tariffs didn’t just change policy — they altered the fundamental economic regime under which the models had been trained, rendering historical patterns temporarily meaningless.
Correlation Breakdown Amplification: When systematic strategies all respond to similar signals, their collective reactions can amplify losses far beyond what individual models predicted. As tariff-sensitive positions moved against multiple quant funds simultaneously during the week of maximum uncertainty, the selling pressure created feedback loops that drove prices further in unfavorable directions.
Execution in Illiquid Markets: RIEF’s longer holding periods meant the fund couldn’t quickly exit positions when regime patterns shifted. As markets panicked, bid-ask spreads widened dramatically and traditional liquidity providers stepped back, turning what should have been modest rebalancing into major portfolio disruptions.
Market Microstructure: When Models Meet Reality
Beyond systematic strategy vulnerabilities, RIEF faced execution challenges that quantitative models often underestimate. As markets reacted to the tariff announcement, bid-ask spreads widened dramatically across equity markets. The fund’s algorithms, calibrated for normal market liquidity, suddenly faced transaction costs far higher than their models anticipated.
High-frequency traders, who typically provide market liquidity, pulled back as volatility spiked and correlation patterns shifted unpredictably. This created a self-reinforcing cycle: systematic funds needed to rebalance positions as their models flagged regime changes, but the act of rebalancing in illiquid markets drove prices further in unfavorable directions.
The phenomenon illustrates a key weakness in factor-based strategies: their models typically assume liquidity will be available when needed. But during true regime changes, liquidity often evaporates precisely when systematic funds need it most, turning what should be modest adjustments into major portfolio disruptions.
Lessons for Quantitative Researchers: Building Anti-Fragile Models
RIEF’s Liberation Day disaster offers three critical insights for quantitative finance practitioners:
Historical Data Has Expiration Dates: The most sophisticated statistical models are only as reliable as the regimes they’re trained on. RIEF’s algorithms had decades of data showing how markets behaved under relatively stable trade policies. But that data became immediately irrelevant when Trump fundamentally altered the rules governing international commerce. Successful quantitative strategies must build robust regime detection mechanisms that can identify when historical relationships are breaking down and react accordingly.
Factor Strategies Need Dynamic Adaptation: Traditional factor models assume underlying economic relationships remain stable over time. But as RIEF learned, factors can suddenly invert when policy changes the fundamental drivers of asset prices. Modern systematic strategies need real-time regime detection that can recognize when factor relationships are shifting and adjust exposures before massive losses accumulate.
Risk Management Must Stress-Test Impossible Scenarios: RIEF’s risk models likely assumed diversification across factors would provide downside protection. But when correlations shift dramatically, diversification disappears precisely when it’s needed most. Effective risk management for systematic strategies must stress-test against scenarios where historical correlations completely break down — even if those scenarios seem improbable based on historical data.
The broader lesson transcends any single strategy or firm. Quantitative finance has grown increasingly sophisticated, but that sophistication creates its own vulnerabilities. Models trained on decades of data can become overconfident in patterns that may not persist when fundamental conditions change overnight.
The Speed Advantage: Why Holding Period Matters
Perhaps the most revealing aspect of RIEF’s failure is the theoretical contrast with how Medallion’s approach might have handled the same shock. While Medallion’s specific performance during April 2025 hasn’t been publicly disclosed, the structural differences between the strategies highlight a fundamental trade-off in systematic investing.
Medallion’s ultra-short holding periods — measured in hours or days — theoretically allow rapid adaptation when market regimes shift. When Liberation Day altered correlation patterns, high-frequency strategies could potentially recognize the change and adjust within the timeframe of maximum market disruption. RIEF’s six-month to one-year holding periods meant the fund remained committed to positions based on relationships that had temporarily stopped working.
This contrast illustrates a crucial principle: longer holding periods can capture persistent market inefficiencies but create vulnerability to regime changes. Shorter periods allow rapid adaptation but may miss slower-developing opportunities. There’s no optimal solution — only different risk profiles that perform better or worse depending on market conditions and the speed of regime changes.
Building Tomorrow’s Quantitative Strategies
RIEF’s Liberation Day loss demonstrates why successful systematic investing requires more than sophisticated algorithms and historical backtests. It demands strategies that can not only survive regime changes but potentially profit from the volatility they create.
Anti-fragile quantitative strategies might incorporate several design principles: dynamic factor allocation that adjusts based on real-time regime detection algorithms, position sizing that accounts for model uncertainty rather than just statistical confidence, and execution systems that can operate effectively when traditional liquidity disappears.
Most importantly, they require intellectual humility about the limits of historical data and the possibility that tomorrow’s markets may operate under fundamentally different rules than yesterday’s. The most dangerous assumption in quantitative finance is that patterns learned from the past will continue to work when the underlying economic regime shifts.
Renaissance Technologies’ RIEF learned this lesson at the cost of $1.6 billion during a single week in April 2025. The challenge for the next generation of quantitative researchers is building strategies that can adapt to regime changes as quickly as they occur — before the market teaches its own expensive lessons.
This analysis is based on publicly reported performance data from verified financial news sources. Renaissance Technologies declined to comment on specific strategy details or attribution analysis. The exact mechanisms of RIEF’s losses and specific factor exposures during April 2025 have not been publicly disclosed by the firm.
Sources:
Financial Times reporting via Investing.com: “Renaissance Technologies hedge fund suffers 8% loss in April post tariffs”
Institutional Investor: “Renaissance’s 2024 Rebirth” and fund performance data
Wikipedia: Liberation Day tariffs and related market impacts
CSIS: “Liberation Day Tariffs Explained” and China impact analysis
Penn Wharton Budget Model: Effective tariff rates and revenue data
White House official announcements and Executive Order documentation
Various verified financial news sources and policy announcements
Methodology Note: Loss calculations based on publicly reported 8% decline applied to estimated $20 billion AUM as reported by Institutional Investor. Market performance data reflects specific daily moves following the April 2 announcement and subsequent April 9 policy modification. China tariff rates from official government sources and trade policy trackers.
Cover photograph: The White House, public domain, via Wikimedia Commons.