
The claim: The number every outlet ran this week, $250,000 into $60 million, a 240x gross return, requires Thirty Five Ventures to hold 0.465% of Hugging Face at closing. No filing, no company statement and no spokesperson has disclosed a percentage. The two documents Hugging Face did file with the SEC, plus its own funding announcements, put Kevin Durant in four financing rounds. The multiple everyone quotes uses two.
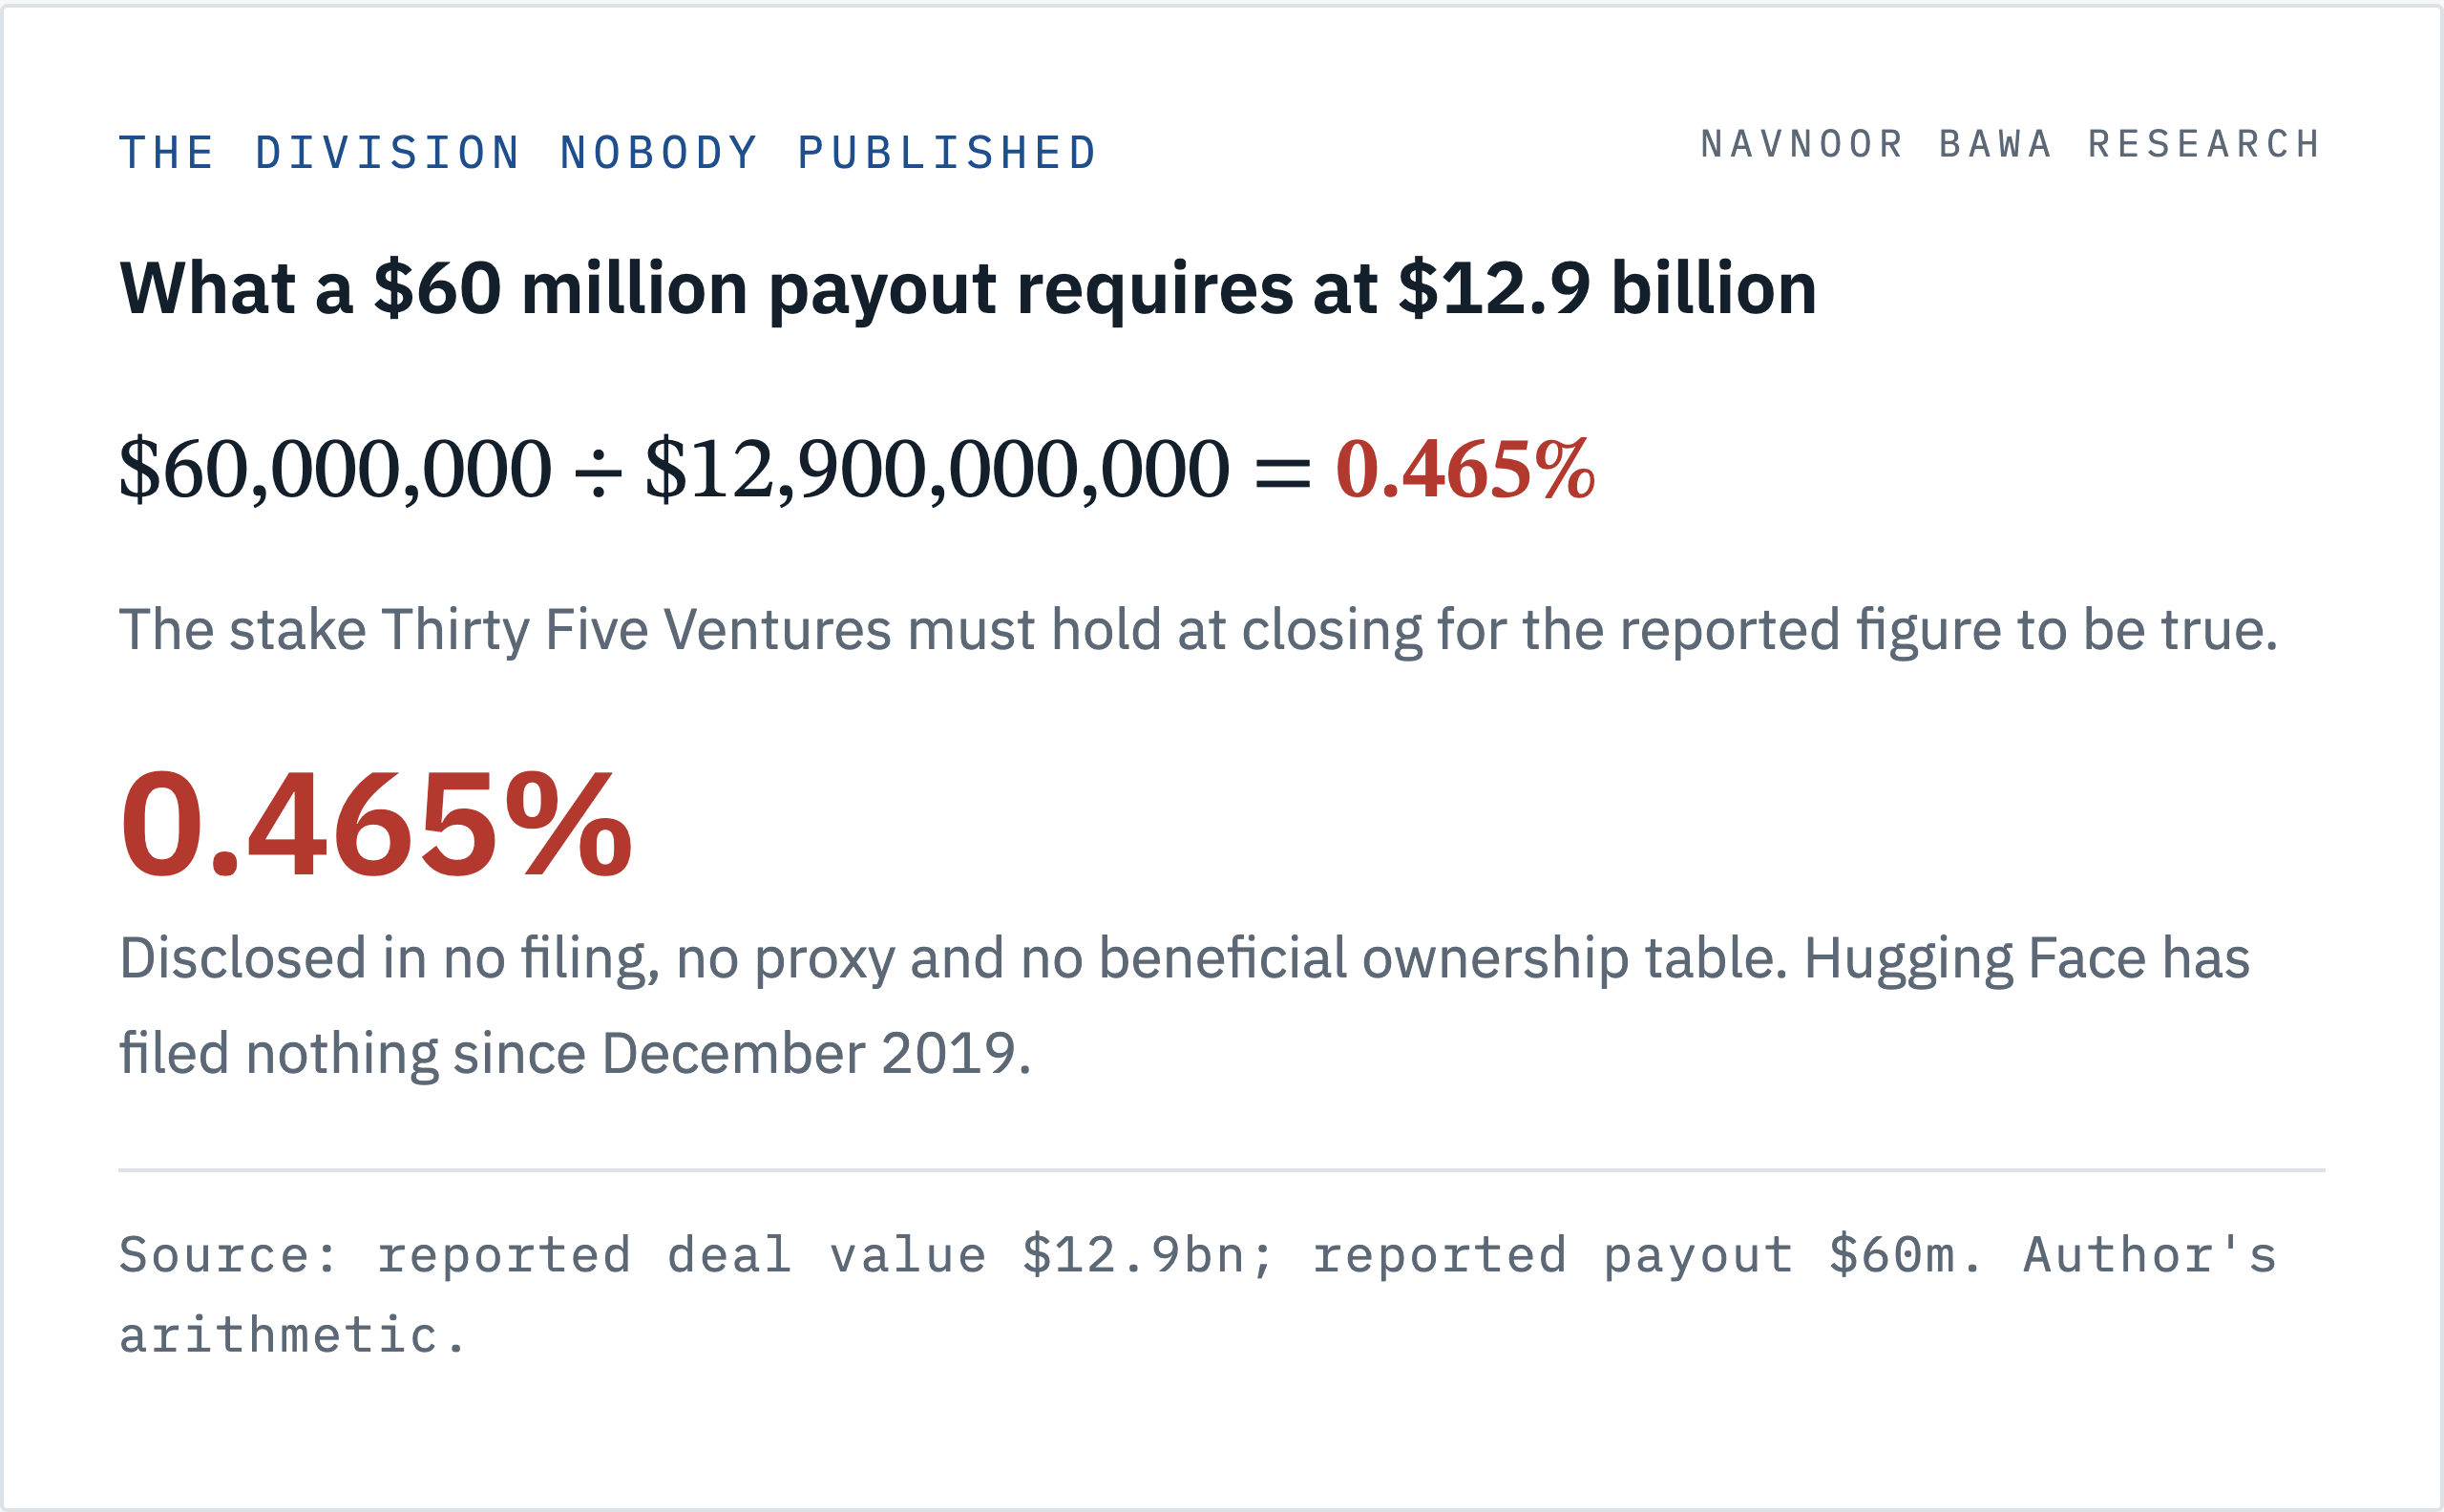
The numbers: Hugging Face’s 2018 seed Form D reports $3,315,000 sold against a $4,000,000 offering, to six investors, in debt. The 2019 Series A Form D reports $19,710,523 sold to 30 investors and states on its face that the figure includes conversion of the earlier notes. $60,000,000 divided by $12,900,000,000 is 0.465%.
The catalyst: The acquisition is reported and unconfirmed, and the two outlets that broke it disagree. The Information reports an agreed deal at $12.9bn; Business Insider reports talks that “had not yet produced a signed agreement.” The payout stories ran on the 27th and 28th.
Wrong if: Thirty Five Ventures discloses that its Series B and Series C checks were immaterial, or Durant’s closing stake is confirmed near 0.465% on a $250,000 basis. Either kills this and I withdraw it.
Nvidia has agreed to buy Hugging Face, the repository where open AI models are hosted and downloaded, for $12.9 billion. Inside a day the second story had eaten the first. Kevin Durant put in $250,000. Kevin Durant is getting $60 million. Twenty-four thousand percent.
I went looking for the cap table behind that arithmetic, expecting a disclosed stake and a lazy multiplication on top. The stake isn’t there. So I pulled Hugging Face’s own SEC filings and read the fields one at a time, then checked the investor list of every round it has announced. Both contradict the coverage.
Below the paid line:
The $60,000,000 sensitivity table line by line: what 240x becomes on a $500,000 basis then a $750,000 basis then $1,250,000 and finally $2,250,000 against the 6.45x ceiling every Series C dollar drags it toward
Both Form Ds field by field: the
isDebtTypeflag that makes the seed’s ownership unobservable, and the clarification that counts $3,315,000 twiceThe verbatim investor lists from TechCrunch’s March 2021 Series B and Hugging Face’s own Series C post, the two documents that break the denominator
Why both headline numbers are wrong and move in opposite directions, plus the 0.465% stake the payout silently requires
Nvidia’s own position in the $235 million Series D, and the $42.3 billion of unnamed private stakes on its balance sheet
Four confounds I cannot rule out, including the 10% to 20% escrow convention and the unsigned agreement
The $60 million traces to four words, and neither of them is a filing
Provenance first, because everything else depends on it. Bleacher Report attributes the figures to one origin: “Insider Joe Pompliano reported Thursday that Durant and his business partner, Rich Kleiman, invested $100,000 in the seed round and $150,000 in the Series A round.” The payout sentence is quoted from him: “He likely made more than $60 million in this investment alone.”
Two words carry the whole edifice, as I read it. I’m told, for the check sizes. Likely, for the outcome. That’s the entire evidentiary base, and “one guy on X” is not automatically wrong: Pompliano covers this beat and may have a real source.
I chased the attribution and it doesn’t converge. Bleacher Report credits Pompliano. TheNextWeb credits Front Office Sports and says only “early rounds.” Yahoo Sports credits Front Office Sports for the $250,000, then names nobody for the payout, which it reports as “believed to be upwards of $60 million.” Three chains, none terminating in a document, two of them sharing an origin. No SEC filing anywhere, no Hugging Face statement, no Nvidia statement, no comment from Durant or Kleiman.
Then I watched the hedges fall off. Joe Pompliano wrote “I’m told” and “likely made more than $60 million.” Anthony Pompliano, to a much larger audience, posted “Kevin Durant made $60 million from investing $250,000 in Hugging Face. Insane.” No hedge, no conditional. The whole mechanism in two posts.
Hugging Face filed $3,315,000, and it was a note
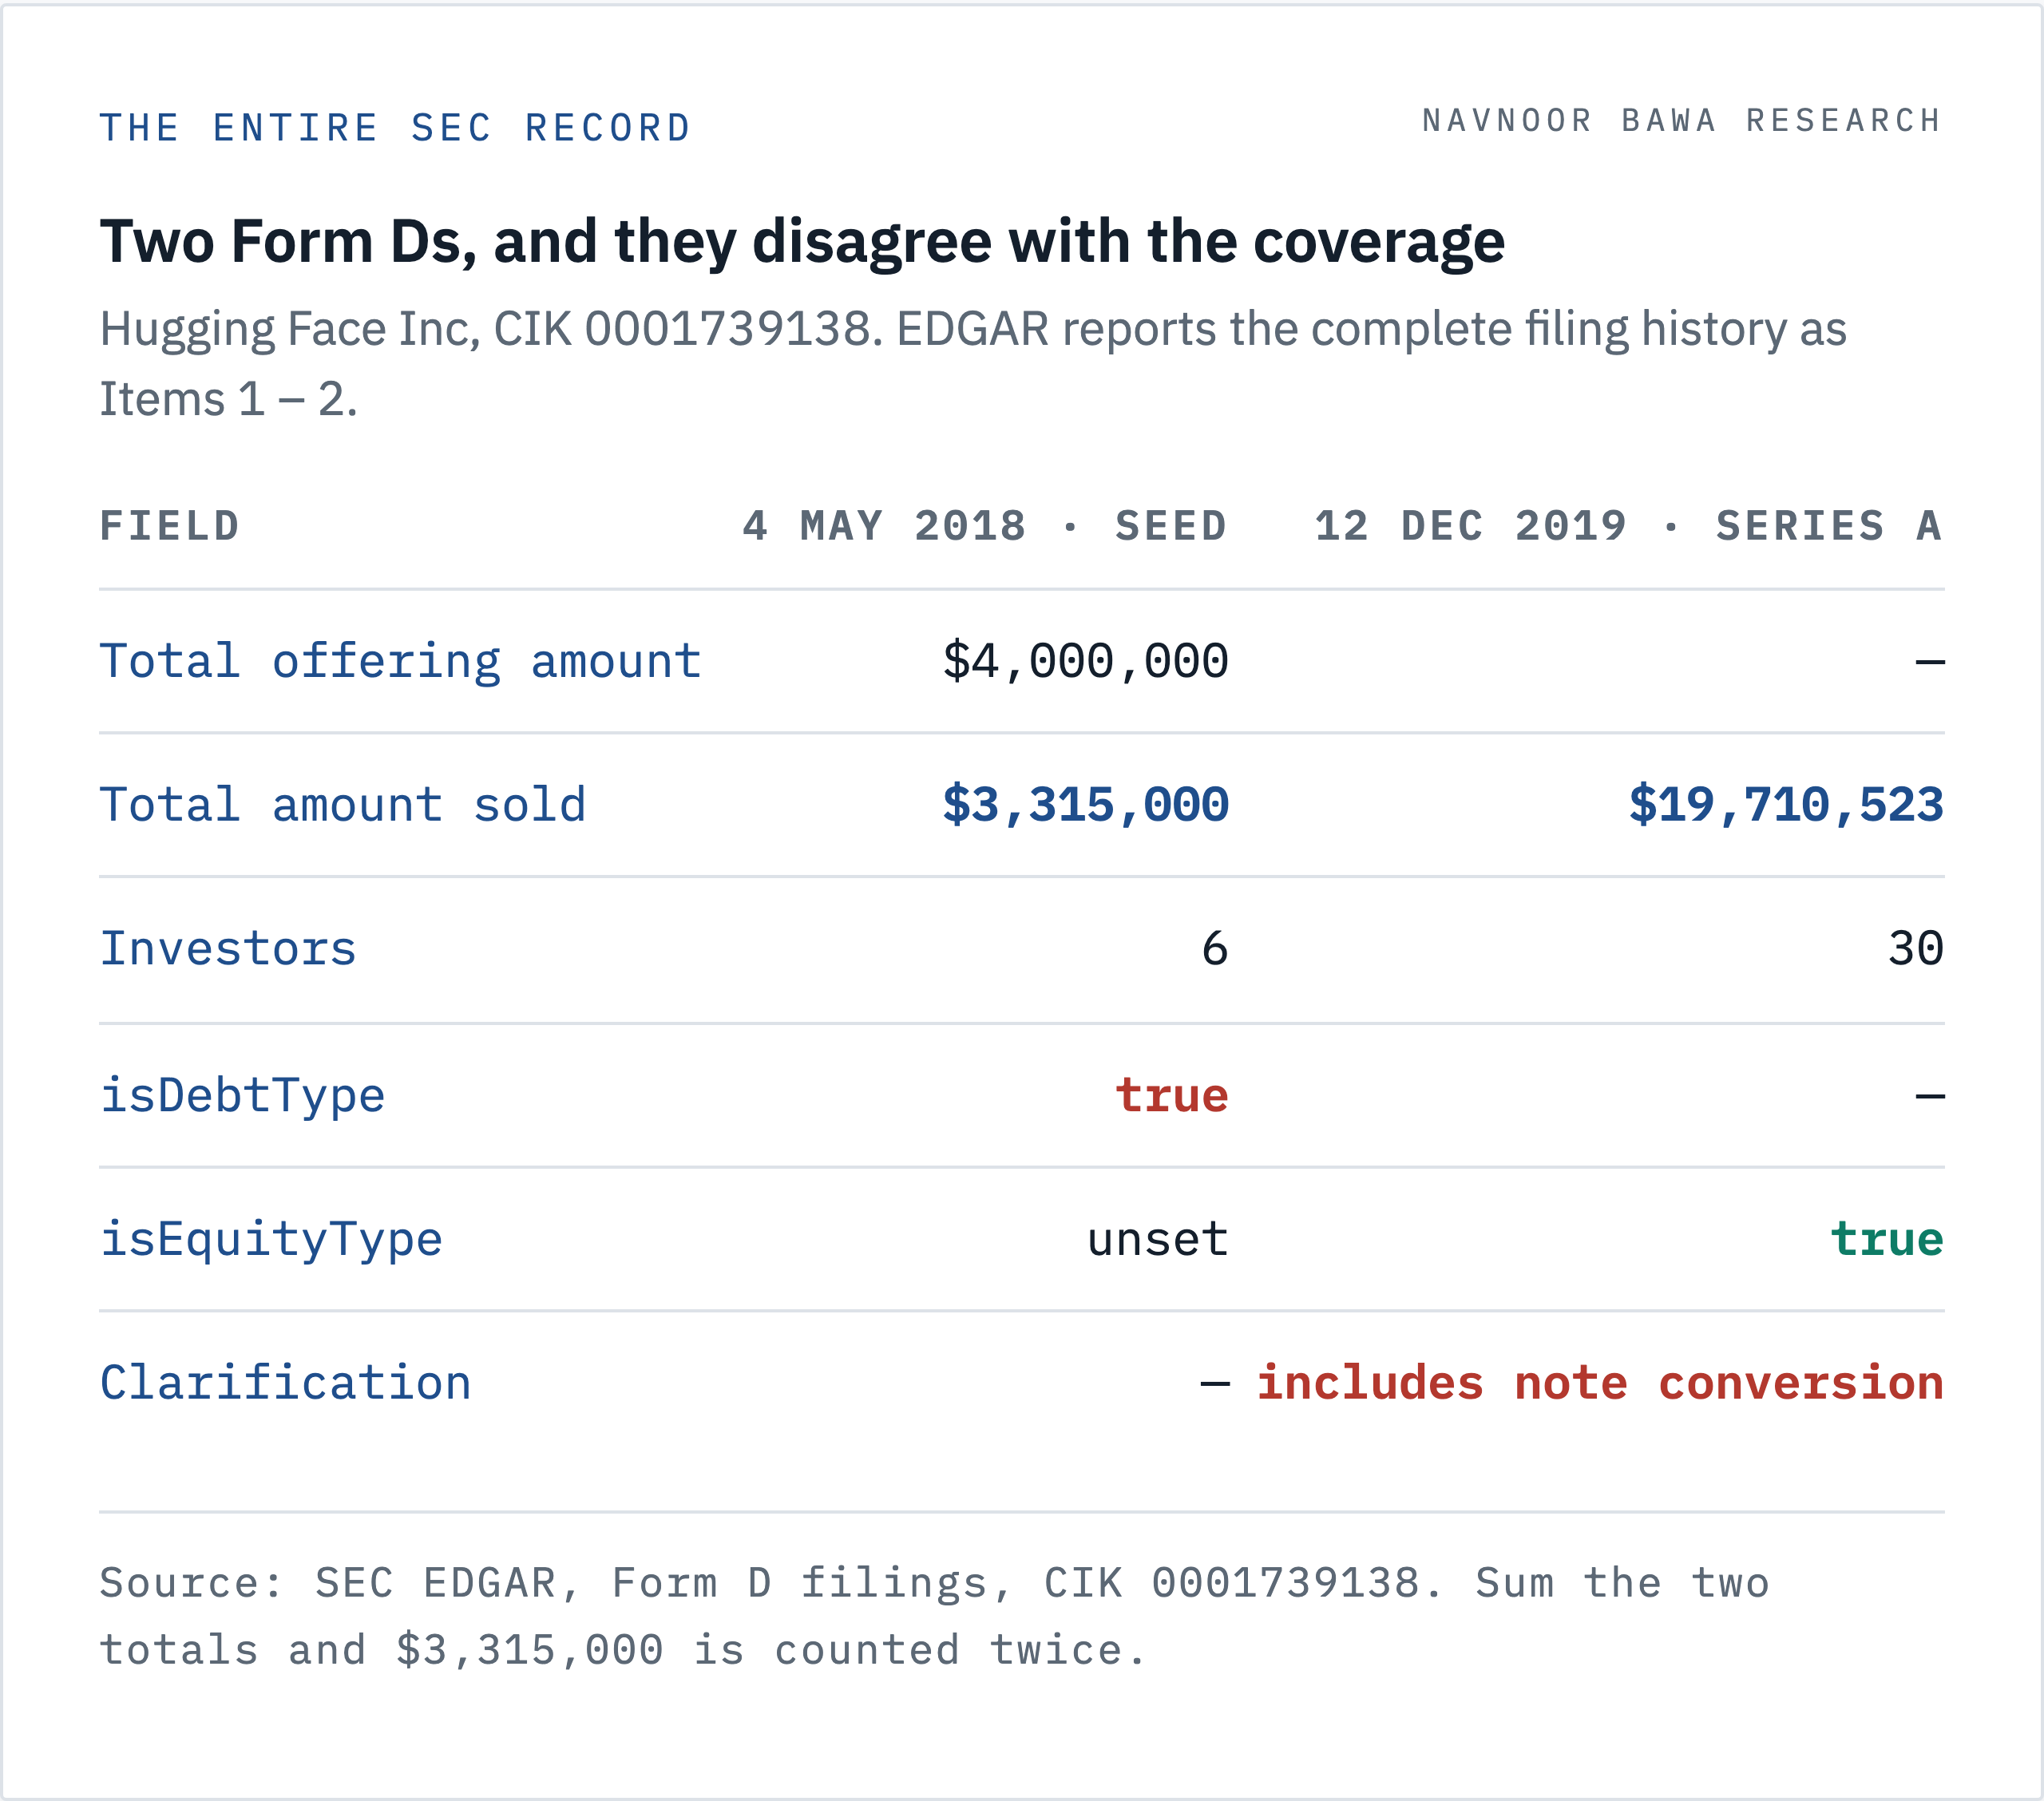
Hugging Face has filed exactly two documents with the SEC in its life. EDGAR returns “Items 1 - 2” for CIK 0001739138, both Form D. The last is dated 12 December 2019.
I pulled the 2018 filing. An offering of $4,000,000, a total amount sold of $3,315,000, first sale 20 April 2018, investors already invested: six. Signed by Julien Chaumond as Treasurer, out of 81 Prospect Street in Brooklyn. Clément Delangue’s name is misspelled “Delange” in the related persons block, which tells you a founder filled it in.
I keep reading “a $4 million seed round,” and I want to be careful about what the filing does and doesn’t prove. Per the SEC’s Form D FAQ, a later change in “the amount of securities sold in the offering” is among the changes that do not require an amendment. The round may well have closed at the full $4 million with nobody obliged to say so. The press figure is the target. The filed figure is the only dated, sourced number in the story.
Here’s the larger one. Under types of securities offered, the 2018 filing marks isDebtType true and leaves the equity flag unset. The seed money bought a convertible instrument. A note or a SAFE, and no stock.
That one field changes what I can say a $100,000 check means. Equity at a price buys a known percentage the day it clears. A note buys a claim that converts later, on terms set by a valuation cap and a discount, and neither appears in a Form D. Nobody outside the cap table can compute what that $100,000 became. That’s a property of the instrument.
The Series A Form D counts the seed money a second time
The 2019 Form D reports $19,710,523 sold to 30 investors, first sale 27 November 2019, equity this time. TechCrunch reported it as a “$15 million funding round” led by Lux Capital, with “A.Capital, Betaworks, Richard Socher, Greg Brockman, Kevin Durant and others.”
The filing explains its own gap, in a clarification field I doubt many people open:
Offering Amount and Amount Sold includes the conversion of convertible notes and Simple Agreements for Future Equity previously sold by the Company into the Equity issued at this offering.
So the $19.71 million isn’t $19.71 million of new money. It holds the 2018 round arriving a second time. Net the $3,315,000 of converting seed paper against it and you get roughly $16.4 million of fresh equity, close enough to the reported $15 million that the two accounts reconcile. Sum the Form D amounts to get “total raised” and you overstate Hugging Face by $3.3 million.
There’s a subtler consequence. The conversion happened at the Series A, so the note’s cap was applied on 27 November 2019 and the share count folded into that round. Durant’s seed and Series A positions were set in one event, and I can’t find their combined percentage published anywhere.
$60 million back solves to 0.465%, and nobody has disclosed a percentage
Now do the division I could not find anywhere in the coverage.
$60,000,000 divided by $12,900,000,000 equals 0.004651. Call it 0.465% of the company at closing, before any escrow, holdback or consideration mix. I give it three figures because the input has about one: every source hedges it as “likely more than” or “believed to be upwards of,” and a quotient cannot be more precise than what went into it.
That is what the reported payout requires. Requires of whom is the next problem. Bleacher Report attributes the $250,000 to “Durant and his business partner, Rich Kleiman,” others attribute it to Thirty Five Ventures, and all of them attribute the $60 million to Durant alone. The firm was founded by both men and I can find no disclosure of how its position splits from Durant’s own economics. Numerator and denominator may not describe the same holder.
Now ask what public evidence supports it. None does. Hugging Face has filed nothing since 2019, and as a private Delaware corporation it owes no 10-K, no proxy, no beneficial ownership table.
Nvidia’s own disclosure doesn’t help, and I went and read it. Note 6 of its April 2026 10-Q reports every private company stake it owns as one aggregate roll forward and names not one of them. Nvidia’s own Hugging Face stake is invisible in Nvidia’s own filings.
So I read 0.465% as a back solve wearing a measurement’s clothes. Pompliano didn’t measure a stake and multiply. He estimated an outcome, and the percentage is what falls out when you divide. I’m not saying the number is too high. My claim is narrower: nobody outside the cap table can produce it, and the coverage presents it as though somebody counted.