


Bottom Line Up Front
Volatility arbitrage strategies delivered mixed results in 2024, with vol-arb funds returning just +2.7% while broader arbitrage strategies managed +5.9% — a stark contrast to the explosive gains some funds achieved using rough volatility models in previous years. This analysis examines how hedge funds identified opportunities through advanced mathematical models, structured positions to capture volatility mispricings, and the critical risk management lessons learned from both successful trades and spectacular failures.
Key Takeaway: Funds managing over $80 billion in arbitrage strategies saw dramatic outcomes in recent market stress, with some losing 40% in a single day during August 2024’s volatility spike — highlighting both the profit potential and existential risks in this space.
The Mathematical Foundation: Why Rough Volatility Models Matter
Traditional volatility models assume smooth, predictable patterns. Reality is different. Rough volatility models emerged from empirical observations that the volatility of financial markets does not behave smoothly. Instead, it displays “roughness,” and needed better quantitative models to represent it accurately.
The rough Bergomi model represents the cutting edge of this evolution. The Bergomi model allows for the volatility of volatility (“vol of vol”). So it considers the variability in the volatility itself, which adds another layer of complexity and realism.
The Mathematical Framework
The rough Bergomi (rBergomi) model uses fractional Brownian motion with Hurst parameter H ≈ 0.1, where log-volatility follows:
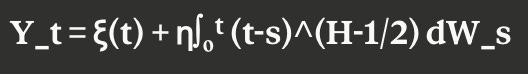
The rBergomi model has only three parameters: H, η and ρ. These parameters have very direct interpretations: H controls the decay of ATM skew ψ(τ) for very short term options, η controls the volatility of volatility, and ρ represents the correlation between price and volatility movements.
Critical Insight: An extensive empirical study of the class of Volterra Bergomi models using SPX options data between 2011 and 2022 reveals the following fact-check on two fundamental claims echoed in the rough volatility literature: rough volatility models are inconsistent with the global shape of SPX smiles. This creates both opportunities and risks for practitioners.
How the Opportunity Was Identified
The Volatility Risk Premium Discovery
Over long periods, index options have tended to price in slightly more uncertainty than the market ultimately realizes. Specifically, the expected volatility implied by SPX option prices tends to trade at a premium relative to subsequent realized volatility in the S&P 500 Index.
This systematic mispricing created the foundation for volatility arbitrage strategies. Hedge funds identified three primary catalysts:
1. Model Mispricing: With neural networks we can compute an entire volatility surface in around 1 millisecond on a standard laptop. A typical calibration to SPX options can then be performed in less than a second. This computational advantage allowed sophisticated funds to spot mispricing faster than competitors.
2. Cross-Asset Opportunities: Knowing that the difference between the VIX and VSTOXX is significant and negative the following ‘naïve’ trading strategy is first investigated. A cross-country spread is entered into, short 100 VIX futures and long a number of VSTOXX futures, creating geographic arbitrage opportunities.
3. Event-Driven Mispricings: Event volatility strategies aim to exploit price inefficiencies and mispricings in implied volatility surrounding specific events, such as earnings announcements or economic data releases. These events often lead to significant price movements, with implied volatility typically rising beforehand due to uncertainty and falling after the announcement.
The Rough Volatility Edge
Rough volatility models have gained prominence in financial mathematics and quantitative finance for their capacity to capture the irregular and complex nature of market volatility. The key advantage: Improved Forecasting — These models provide more accurate short-term volatility forecasts. Important for options pricing and risk management.
However, recent research reveals critical limitations. The rough Bergomi model slightly, but not consistently, outperforms the one-factor (Markovian) Bergomi model in fitting the volatility surface on average, but scores the highest variance. For the period between 2017 to 2019, the rough Bergomi model underperforms the one-factor Bergomi model.
How Positions Were Structured and Risk-Managed
The Classic Volatility Arbitrage Setup
To an option trader engaging in volatility arbitrage, an option contract is a way to speculate in the volatility of the underlying rather than a directional bet on the underlying’s price. If a trader buys options as part of a delta-neutral portfolio, he is said to be long volatility. If he sells options, he is said to be short volatility.
The profit mechanism is elegant: The profit is extracted from the trade through the continuous re-hedging required to keep the portfolio delta-neutral.
Advanced Greeks Management
Beyond basic delta hedging, sophisticated practitioners focused on higher-order Greeks:
Vanna (∂²V/(∂S∂σ)): Cross-sensitivity between spot and volatility
Volga (∂²V/∂σ²): Volatility convexity
Speed and Color: Third-order Greeks for dynamic hedging
Note that the “fair” estimator of the realized skew in equation 4.13 involves the covariance of the spot and the implied ATM volatility, rather than the covariance of the spot and its realized volatility. This insight drove sophisticated risk management frameworks.
Risk Management Failures: The Cautionary Tales
February 5, 2018: The CBOE Volatility Index (VIX) — Wall Street’s “fear gauge” — doubled from 18 to 37 in minutes. LJM Partners collapsed by approximately 80% during the February 2018 volatility spike, with the fund managing hundreds of millions in the morning and facing near-total liquidation by close. Credit Suisse’s XIV ETN, managing nearly $2 billion in assets, terminated after losing 93–97% in a single day.
August 5, 2024: The VIX spiked to 65 — the fastest implied volatility surge ever recorded. Hedge funds with short volatility positions watched their capital vanish as SVXY plummeted 40% and margin calls exploded to 10–30 times initial premiums.
How Returns Were Generated (or Lost)
The Profit Mechanisms
1. Volatility Risk Premium Harvesting: The discrepancy between the realized value of R0 and its model-independent value of 2 pictured in figure 3.3 can equivalently be expressed as a discrepancy between the market ATM skew and the “realized” skew created systematic profit opportunities.
2. Advanced Model Arbitrage: The rough Bergomi (rBergomi) model, which allows rough volatility, can perform better with high-frequency data. However, classical calibration and hedging techniques are difficult to apply under the rBergomi model due to the high cost caused by its non-Markovianity. Funds that solved this computational challenge gained significant edges.
The 2024 Performance Reality
The lowest performing strategy was arbitrage (+5.9%), driven by material underperformance from the arb — tail sub-strategy (-2.9%) and mediocre performance from arb — vol (+2.7%). Much like in 2023, it’s no surprise that tail hedging strategies would underperform in 2024 given the falling realised and implied volatility and negative beta associated with the strategy.
Converting Theory to P&L
Convertible arbitrage emerged as a standout performer in 2025, benefiting from a robust new issuance market and favourable trading conditions. The HFRI RV Convertible Arbitrage Index has returned +4.0% year-to-date, capitalising on opportunities created by a surge in convertible bond issuance in 2020–2021.
The Execution Reality: Convertible arbitrage managers were able to capitalise on the volatility of underlying equities, locking in profits while maintaining hedged positions; for example, technology sector equities experienced significant price swings, creating opportunities for active trading.
Why Some Strategies Failed
While alluring in theory, poor risk controls can crater funds, as highlighted in these cases: LTCM Meltdown — The epic 1998 collapse of fixed income arbitrage pioneer Long Term Capital Management serves as a precautionary tale for the field. Gusty leverage assumptions without macro hedging proved fatal.
The core problem: In periods of high uncertainty regarding future implied volatility, signalled by an increase in the volatility of VIX, volatility arbitrage strategies perform well due to the difficulty of foreseeing the future level of VIX and the existence of more opportunities for volatility trading strategies — but this same uncertainty destroys poorly hedged positions.
Key Principles and Actionable Insights
1. Model Sophistication vs. Implementation Risk
Lesson: On the positive side: our study identifies a (non-rough) path-dependent Bergomi model and an under-parameterized two-factor Markovian Bergomi model that consistently outperform their rough counterpart in capturing SPX smiles between one week and three years with only 3 to 4 calibratable parameters.
Application: Sometimes simpler, more robust models outperform cutting-edge alternatives in real trading environments.
2. Computational Advantage Creates Alpha
Insight: This method features significantly lower input dimensions (i.e. the forward variance curve of the Bergomi model is not part of the NN input). In addition, it is free from butterfly arbitrage by construction and mesh-free, allowing one to price derivatives for any strike and maturity combination without interpolation or extrapolation.
Application: Focus on computational efficiency and arbitrage-free implementations rather than pure model complexity.
3. Risk Management Is Everything
Critical Understanding: The liquid volatility space is highly unusual in exhibiting counter-cyclical liquidity: volumes traded tend to increase in a crisis precisely when liquidity can be evaporating or intermittent in some other markets.
Risk Framework: Build position sizes around worst-case volatility spikes, not average conditions.
4. Geographic and Cross-Asset Diversification
Opportunity: Asia offers relatively cheap volatility pricing due to structured products with affordable embedded options, while North American and European markets tend to see higher implied volatility costs. Relative value volatility arbitrage aims to purchase low-cost volatility and sell more expensive options.
5. Technology Integration
Modern Approach: This paper proposes a gated recurrent unit neural network (GRU-NN) architecture for hedging with different-regularity volatility. One advantage is that the gating network signals embedded in our architecture can control how the present input and previous memory update the current activation.
The Path Forward
The recent turmoil in financial markets has highlighted the importance of volatility arbitrage strategies as a diversification tool for a FOF portfolio. Comparing performance of VTI and main hedge fund strategies over the highly volatile environment from July 2007 to March 2008, we observe that volatility arbitrage proved to be more resilient and outperformed the main hedge fund strategies through the period.
The opportunity remains substantial, but the landscape has evolved. These variations lead to a high degree of heterogeneity across volatility arbitrage funds, with intra-strategy correlations the lowest relative to other hedge fund strategies, suggesting that manager selection and strategy implementation remain crucial differentiators.
Bottom Line: Volatility arbitrage continues to offer compelling risk-adjusted returns for sophisticated practitioners, but success requires robust risk management, computational advantages, and deep understanding of market microstructure — not just theoretical model sophistication.
Sources: Aurum Hedge Fund Research, UBP Alternative Investment Solutions, The Hedge Fund Journal, arXiv Quantitative Finance papers, CBOE Market Data
Cover photograph: SecretName101, CC BY-SA 2.0, via Wikimedia Commons.